
Americans turn to financial advisors for thoughtful, personalized strategies across their financial lives. Workplace retirement accounts should be part of that conversation. Through our work with advisors and retirement savers, we’ve learned firsthand that 74% of retirement savers want professional advice, and that advice can produce up to, or even exceed, 3% in net returns annually. Advice has value, and when clients have a clearer path to put recommendations into action, that value can go further.
But there’s a challenge. Many firms still prefer to stick with a user-controlled non-discretionary advice model. When savers tap advisors for support with their retirement accounts at firms with these non-discretionary requirements, advisors can provide thoughtful recommendations, but, ultimately, the retirement saver must implement that advice. And it’s hard to keep track when those recommendations were implemented and if they were done correctly.
It’s a homework model: “Here’s what I recommend. Now log into your 401(k), find the right place to make the changes, and put that advice into action.”
That can be a lot to ask. Many savers lack the education, expertise, and confidence to do it on their own. That’s why study after study suggests many retirement savers fail to actually implement their advisor’s recommendations, missing out on tax optimization strategies, withdrawal suggestions, performance improvement, and more.
And advisors are often left chasing. Following up. Reminding. Call it what you want, but the outcome remains the same: lots of time, lots of effort, lots of administrative burden, and a lot of finger crossing, hoping the advice gets put into action.
The question is not whether workplace retirement accounts belong in the advice relationship. It is how to support that advice across different firm models.
Closing that gap requires infrastructure that supports the non-discretionary advice model as it actually works: advisor-delivered advice, client-led implementation, and the supervision, monitoring, and documentation firms need around the entire process. .
This isn’t a “white flag” moment; rather, this is a natural progression that expands Pontera to firms who otherwise would not be able to use the product within their non-discretionary requirements. We’re thrilled to widen the scope of our user base with this new mode.
What is the Non-discretionary model?
Non-discretionary advice is a new mode within the Pontera platform that helps firms deliver workplace retirement account recommendations while keeping implementation in the client’s hands. Advisors can deliver personalized recommendations through Pontera, clients receive a guided experience to take action, and firms maintain the oversight, notifications, and controls needed to supervise the process.
Expanding how firms can serve retirement savers
For years, Pontera has helped firms bring workplace retirement accounts into holistic advice through secure, advisor-managed workflows.
When speaking with advisors and end clients, we heard a consistent theme: the current non-discretionary workflow can be difficult for advisors, confusing for clients, and hard for supervision teams to scale. So we asked what a better experience could look like.
Here’s some of the feedback we got from firms:
“Our advisors provide recommendations and action steps for clients to complete and kind of leave it in the hands of the client to actually make those changes.”
“We’ve got plenty of folks with 401(k)s. This would make it more efficient to incorporate that into planning advice, but also check in if they didn’t do what they said they were going to do.”
”It’s what we have now, absent the automated process. Any ability to make the advisor and the process more efficient is something we should actively be thinking about.”
The friction shows up across the full workflow, with a long laundry list of to-dos:
Advise clients on which plan documents to send and where to find them
Extract that information into a portfolio management system
Communicate recommendations in a clear and helpful way
Help clients navigate their 401(k) provider’s website
Determine whether the client implemented the recommendation correctly
Because every retirement plan portal is different, and those portals can change over time, even well-intentioned follow-up can become inconsistent and time-consuming. For clients, that can fall short of the clear, guided experience they expect.
And when advisors end up guiding clients across emails, calls, meetings, and other one-off communications, supervision teams may lack a centralized, scalable way to review those recommendations, monitor progress, and maintain a clear record of what happened.
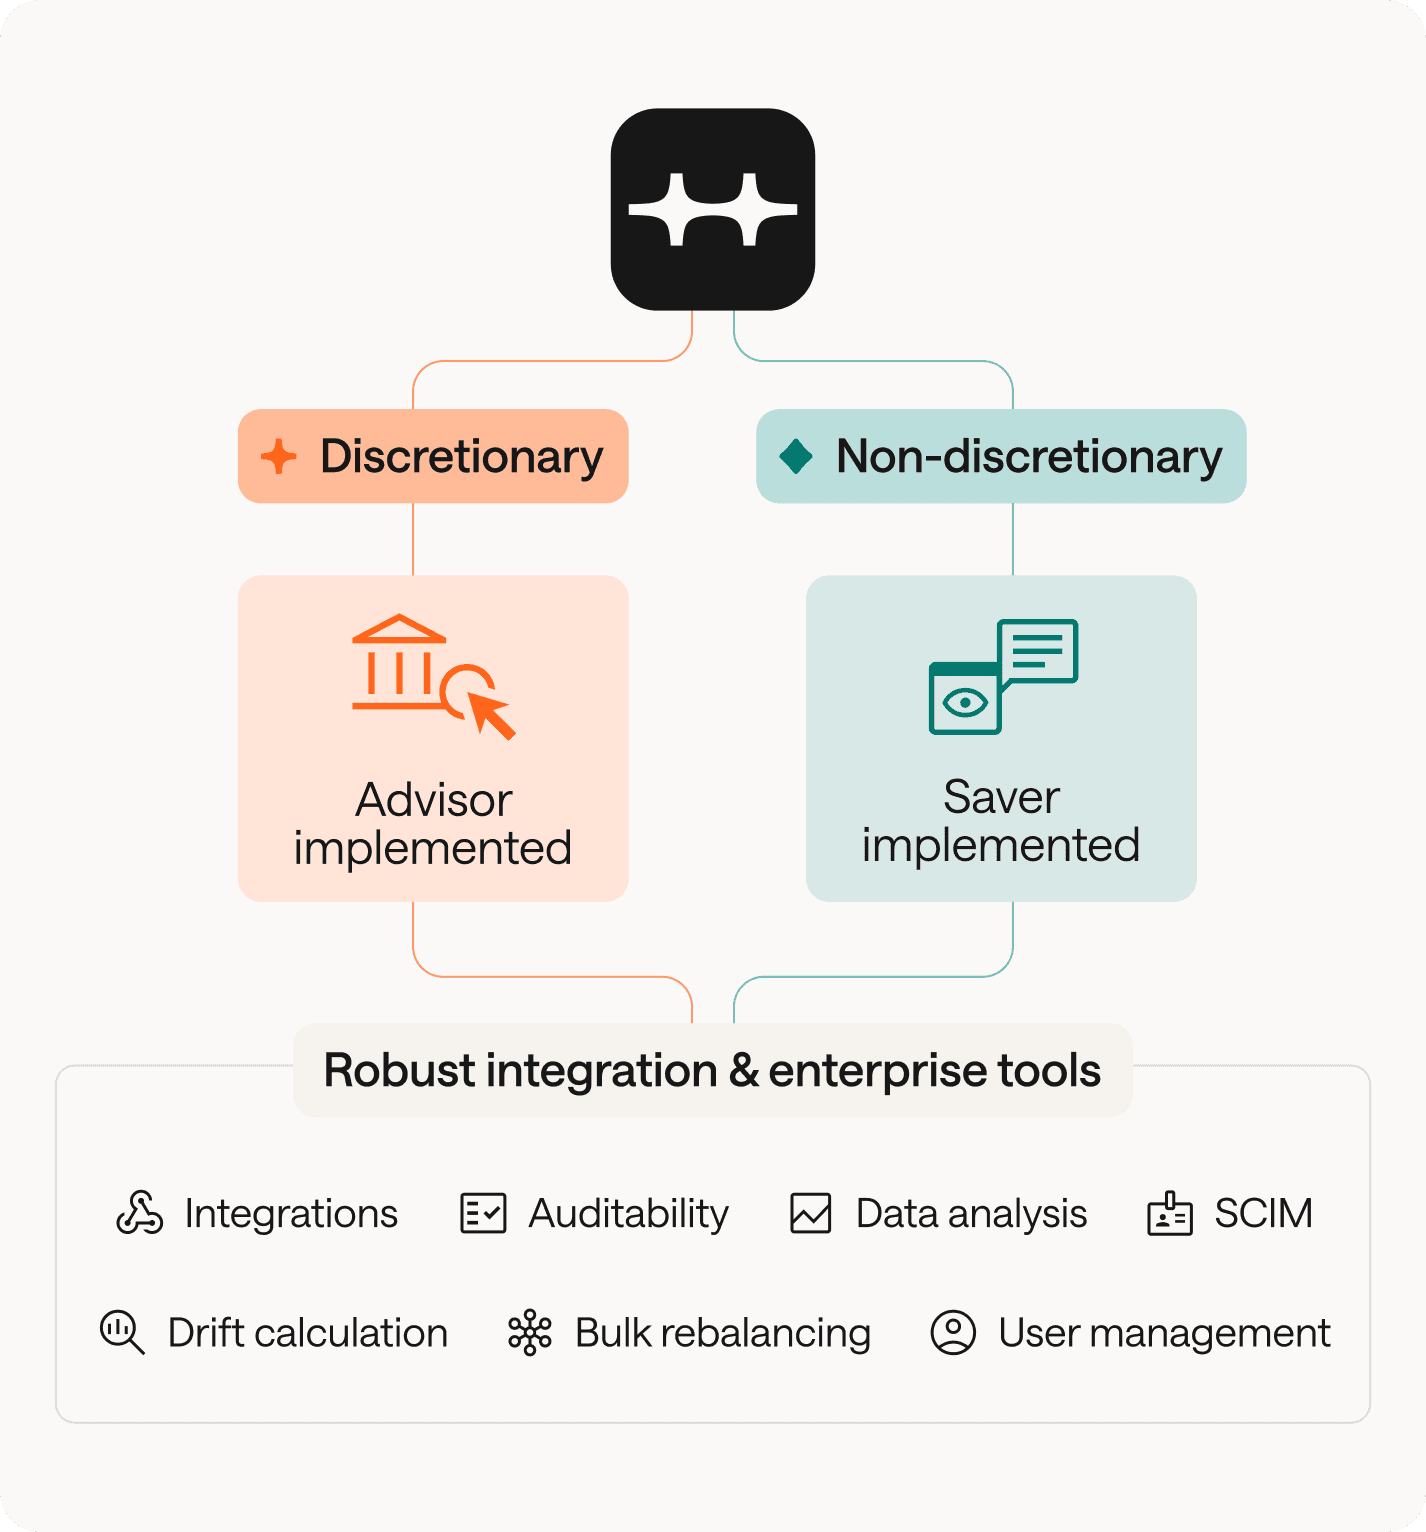
But the value doesn't simply lie within the standardization and automation. Pontera’s new Non-discretionary Advice Workflow goes well beyond general aggregation, adding enterprise-grade functionality, including plan document guidance, data extraction, drift calculation, rebalancing recommendation infrastructure, supervision alerts, audit trails, reminders, and implementation confirmations. Clients receive a secure, step-by-step experience to put those recommendations into action with more confidence.
The result is a more coordinated experience: advisors can focus on delivering advice, clients have a clearer path to act on it, and compliance and supervision teams can track and review the process in one place.
More choice for retirement savers starts with more choice for firms.
Workplace retirement accounts are too important to sit outside the financial planning conversation. Whether firms provide discretionary management or advice that clients implement themselves, retirement infrastructure should support the way they serve their clients.
The future of retirement advice isn't about asking every firm to work the same way. It's about ensuring more firms can help retirement savers benefit from professional advice while operating in the way that's right for their business. With support for both discretionary and non-discretionary models, Pontera gives firms more flexibility in how they serve clients while maintaining robust infrastructure for workplace retirement account advice.
Helping people retire better starts with giving firms more ways to meet clients where they are and supporting more than one path from recommendation to action. We’re continuing to listen closely to advisors, firms, and retirement savers as we expand the platform toward a future where everyone can benefit from personalized advice across their entire financial lives.
Interested in learning more about Pontera’s Non-discretionary advice offering?
Stay ahead with insights on modern retirement
Unsubscribe anytime